Link copied!
Vertical comparison
Fintech CPA offers: lending vs trading vs insurance commissions
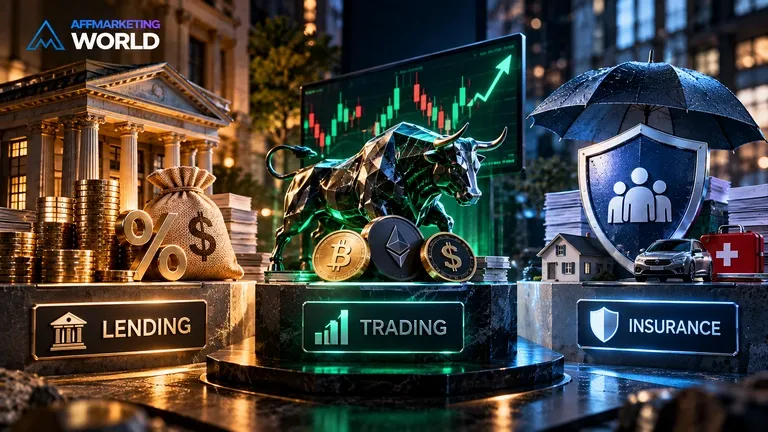
"Fintech" on a CPA network’s offer wall covers three businesses that have almost nothing in common. A loan, a funded trading account, and an insurance policy are sold to different people, regulated by different bodies, and paid out on completely different timelines. Treating them as one vertical is how affiliates end up applying lending intuition to a trading offer and wondering why the payout got clawed back three weeks later.
Here’s what actually separates them — and which one fits the traffic you already have.
Three businesses wearing one label
Lending sells access to money now, against a promise to repay later — personal loans, payday loans, BNPL, microloans. The affiliate’s job is volume: get an application in front of someone who needs cash and qualifies.
Trading sells access to a market — forex, CFDs, crypto exchanges, stock brokers. The affiliate’s job is qualification: a funded, active account is worth far more than a signup, and the network knows it.
Insurance sells a promise against a future event — auto, health, life, travel. The affiliate’s job is patience: the sales cycle from quote to bound policy is the longest of the three, and payout follows it.
Side by side
| Aspect | Lending | Trading | Insurance |
|---|---|---|---|
| Typical payout | $5–$80 CPA | $200–$1,000+ CPA, or RevShare on spread | $10–$150 CPA/CPL |
| Payout trigger | Approved or funded loan | Funded deposit + min. trade activity | Quote request (low) or bound policy (high) |
| Time to payout | Days | Days, but clawback window 30–90 days | 30–90 days for bound policies |
| Compliance load | High — APR/term ad restrictions | Very high — FCA/CySEC/ASIC-adjacent rules | Moderate — licensing varies by GEO |
| Biggest risk | Ad account bans on loan-ad policy | Clawback if trader withdraws fast | Lead rejected if policy never binds |
| Best GEOs | PH, MX, NG for volume; US/UK for payout | Markets with retail trading demand, light ad restriction | US (open enrollment), travel-heavy GEOs seasonally |
What actually goes wrong in each
Lending: the ad account dies first
Google and Meta both restrict loan advertising by APR and repayment term, and require certification in several countries. Most lending affiliates lose their first ad account to a policy violation before they lose a single lead to fraud — read the platform’s personal loan policy before you build the campaign, not after it gets rejected.
Trading: the payout isn’t final until it is
A funded account looks like a win, but most contracts allow a 30–90 day clawback window — if the trader withdraws immediately, never places the minimum number of trades, or the account gets flagged internally, the commission reverses. The signup was never the finish line; the network is watching what happens after.
Insurance: the lead is only half the sale
A quote request pays little and fast. A bound policy pays well and slow — 30 to 90 days, because the insurer has to actually issue the policy before the network will confirm it. Affiliates who plan cash flow around quote-volume numbers get caught out when the higher-value bound-policy payouts arrive months later than expected.
CPA vs RevShare — which model fits which niche
- Lending almost always runs CPA — there’s no ongoing relationship to share revenue from once the loan is funded or declined.
- Trading offers both, and the choice matters: CPA pays once and is done, RevShare pays a small ongoing share of the trader’s activity — better for traffic that produces long-term active traders, worse for traffic that converts once and disappears.
- Insurance is almost always CPA or CPL on the quote or bind event — there’s no revshare-style ongoing commission structure in most consumer insurance affiliate programs.
- If you’re not sure which your traffic fits, start CPA on all three — RevShare only pays off once you have enough historical data to know your traffic retains.
Don’t run all three on the same traffic source
Lending, trading, and insurance audiences don’t overlap as cleanly as "finance" traffic suggests. A source that converts well on payday loan intent rarely converts on trading intent, and vice versa — matching offer to audience matters more here than in most other verticals.
“
"Fintech" is a billing category, not a strategy. Lending rewards volume and survives on ad-policy discipline. Trading rewards patience past the signup and survives on reading the clawback clause. Insurance rewards a longer runway and survives on not confusing a quote for a sale. Pick one that matches the traffic you actually have, not the one with the biggest number on the offer wall.

Frequently asked questions
1
Which fintech niche pays the most per lead?
Trading, by a wide margin — a funded CFD or forex account can pay $200–$1,000+. But it also carries the most clawback risk: the payout is tied to the trader staying active and funded, not just signing up.
2
Can I run loan offers on Google Ads or Meta?
Only within strict limits. Both platforms restrict short-term/payday loan advertising by APR and repayment term, and require certification in several countries. Read the platform’s personal loan policy before building a campaign — a rejected ad account is a common first mistake here.
3
Why did my trading commission get clawed back after I was already paid?
Most trading networks pay on a conditional basis — the deposit has to clear, sometimes a minimum number of trades has to execute, and some contracts allow a clawback window of 30–90 days if the account gets flagged or the trader withdraws immediately. Read the contract’s clawback clause before you scale a source.
4
What’s the difference between CPA and RevShare in trading?
CPA pays once, per funded account, regardless of how much the trader goes on to trade. RevShare pays an ongoing share of the spread or commission the broker earns from that trader over time — smaller upfront, but compounding if the trader stays active for months.
5
Is insurance a good niche for someone starting out?
It’s more forgiving on compliance than trading and less aggressively regulated than lending, but the payout delay (30–90 days for policy-bound offers) makes it a slow niche to learn cash flow on. CPL-based quote offers pay faster and lower, and are the easier entry point.
6
Which GEOs work best for microloan and lending offers?
The US and UK have the highest payouts but the strictest ad policy enforcement. Emerging markets — the Philippines, Mexico, Nigeria — have lower CPA but far less friction getting campaigns approved, which is why a lot of lending affiliates start there.
See the finance offers ranked side by side
Compare live CPA and CPL rates across lending, trading, and insurance networks currently on the platform.
Related tags


Share
SUBSCRIBE TO OUR PRIVATE CASES AND USEFUL TIPS
Subscribe to our newsletter, get only exclusive content and weekly digests, no any spam!
By providing my email, I accept the Privacy Policy.